Social Security Claiming: Understand Your Options

Explore claiming ages, household needs and the connection between Social Security and retirement protection. Anil Khanchandani, CLTC®, a licensed insurance producer, provides education to help you prepare questions for Social Security and your tax or financial professionals.

Read the 2027 Social Security COLA update or explore Medicare coverage and enrollment.

Why Your Claiming Age Matters

Your claiming age affects your monthly retirement benefit. The right timing depends on your earnings record, household needs, health and other income. Compare your own Social Security estimates rather than relying on another person’s benefit or a national maximum.

Anil Khanchandani, CLTC®, provides education about how insurance protection and retirement needs fit together. For official benefit estimates, eligibility and filing decisions, use Social Security’s resources and consult the appropriate professional for tax or investment advice.
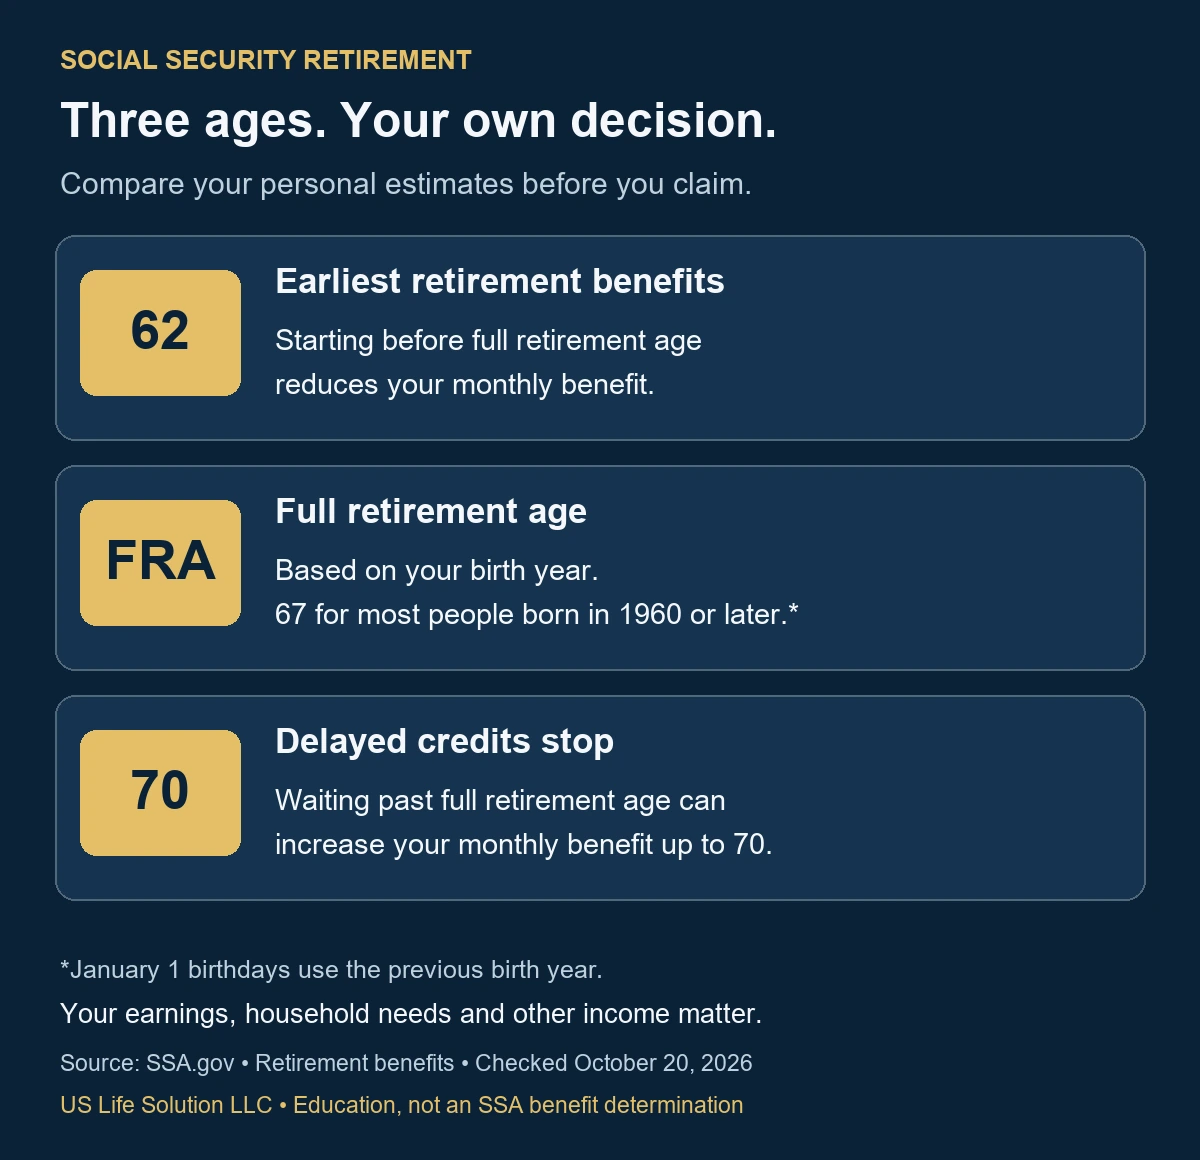
Social Security retirement claiming ages: 62 is the earliest starting age with a reduced monthly benefit; full retirement age depends on birth year; delayed retirement credits stop at 70. Compare your own SSA benefit estimates.
Age 62: retirement benefits can begin with a reduced monthly amount. Full retirement age depends on birth year (67 for most born in 1960 or later; January 1 birthdays use the previous year). Delayed retirement credits stop at 70. Compare your own SSA estimates.

Social Security in 2026: The Numbers That Matter

These figures come directly from the Social Security Administration's 2026 announcements and are updated annually.

Cost-of-Living Adjustment (COLA) 2.8% Benefits rose 2.8% in January 2026
Average retired-worker benefit ~$2,071/month A baseline — your number depends on your record and claiming age
Maximum benefit at age 62 $2,969/month Early claiming permanently reduces your check
Maximum benefit at age 70 $5,181/month Delayed retirement credits add ~8% per year past full retirement age
Full Retirement Age (FRA) 67 (born 1960 or later) The pivot point for reductions and credits
Earnings limit (under FRA all year) $24,480 $1 withheld for every $2 earned above this if you work while collecting early
Earnings limit (year you reach FRA) $65,160 $1 withheld for every $3 above this, until the month you reach FRA
Maximum taxable earnings $184,500 Wages above this aren't taxed for Social Security — and don't increase your benefit

Source: Social Security Administration, 2026 Cost-of-Living Adjustment Fact Sheet (ssa.gov/cola). Figures change annually.

The 6 Most Common Social Security Mistakes — and How I Help You Avoid Them.

Claiming Too Early Without Running the Numbers

The problem: Nearly everyone is eligible at 62, and many claim the moment they can. But claiming at 62 with a full retirement age of 67 permanently reduces your benefit by about 30% — for life, and it reduces the survivor benefit your spouse may one day depend on.

How I help: Before you file, we map your break-even ages, health and longevity outlook, household income needs, and survivor implications side by side — so "earliest" and "best" aren't confused with each other.

Leaving spousal, survivor, or divorced-spouse benefits on the table

The problem: A lower-earning spouse may be entitled to up to 50% of the higher earner's full benefit. Widows and widowers can claim survivor benefits as early as 60. If you were married 10+ years and divorced, you may claim on your ex-spouse's record without affecting their benefit. Most people don't know which of these applies to them — and SSA staff won't proactively optimize for you.

How I help: I review your household as a unit — both records, both ages, both life expectancies — because the right strategy for a couple is almost never two individual decisions made separately.

Working while collecting and getting hit by the earnings test

The problem: If you collect before full retirement age and keep working, Social Security withholds $1 for every $2 you earn above $24,480 (2026). People are routinely blindsided by withheld checks or overpayment notices they're asked to repay.

The good news most people don't know: withheld amounts aren't lost forever — your benefit is recalculated at full retirement age. But the cash-flow surprise is real.

How I help: We project your earnings against the limit before you file, so you know exactly what to expect — or whether waiting a year or two changes everything.

Triggering avoidable taxes on your benefits

The problem: Up to 85% of your Social Security can become federally taxable once your "combined income" passes $34,000 (single) or $44,000 (married filing jointly) — and the thresholds start at just $25,000/$32,000. A poorly timed 401(k) withdrawal or rollover in the wrong year can push more of your benefit into taxable territory. O

ne bright spot for NJ residents: New Jersey does not tax Social Security benefits on the state return.

How I help: I coordinate your claiming timeline with your retirement account withdrawal strategy — see my 401(k) Rollovers and Retirement Strategies pages — so income lands in the right years. (I'm not a tax advisor; for tax filing decisions, I'll encourage you to confirm with your CPA.)

Ignoring the Social Security–Medicare connection

The problem: Social Security and Medicare are joined at the hip: Medicare Part B premiums are deducted from your Social Security check, higher income can trigger IRMAA surcharges on your premiums, and missing your Medicare enrollment window at 65 — because you delayed Social Security and assumed Medicare would wait too — can mean lifetime penalties.

How I help: This is where one-stop planning earns its keep. I'm a licensed Medicare strategist as well — your claiming age, Medicare enrollment, and premium exposure get planned together, not in silos. Start with my Medicare resource hub.

Outdated assumptions about pensions (WEP/GPO)

The problem: For decades, teachers, police, firefighters, and other public servants with non-covered pensions had benefits reduced by the Windfall Elimination Provision and Government Pension Offset. The Social Security Fairness Act, signed January 5, 2025, repealed both — and millions of affected retirees received adjusted payments. Yet many people are still planning around rules that no longer exist, or never went back to claim what they're now owed.

How I help: If you or your spouse have a government pension, we revisit your numbers under the current law — not the law you remember.

Connect Social Security with Your Other Planning Questions

Your claiming decision can affect household cash flow alongside Medicare costs and enrollment, employer retirement-plan options, life insurance and estate liquidity, and long-term care planning.

Start with your questions and current coverage. Anil explains insurance options in states and product lines where he is licensed and appointed, and encourages coordination with your CPA, attorney and registered investment professional when needed.
Advisor meeting with smiling senior clients

Get Clarity Before You Claim

Have questions before filing, or want to understand your current benefits alongside insurance needs? Book an educational conversation with Anil. There is no service fee and no obligation to purchase insurance. He receives commissions from insurance carriers.

For eligibility, application changes or benefit corrections, confirm the rules and deadlines directly with Social Security. See the latest COLA update or browse the education center.

Frequently Asked Questions About Social Security

US Life Solution LLC and Anil Khanchandani are not affiliated with, endorsed by, or connected with the Social Security Administration or any other U.S. government agency. This page is for educational purposes only and does not constitute legal, tax, or investment advice. Social Security figures shown are for 2026 and change annually; verify current amounts at ssa.gov. For decisions about your individual benefits, you may contact the Social Security Administration at 1-800-772-1213 or ssa.gov. Anil Khanchandani, CLTC®, is a licensed life and health insurance producer in 24 states (California license #4428939). Insurance assistance is limited to states and product lines where he is licensed and appointed.